Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

2 min read

What Lenders Look For: Eligibility, Income, and Debt-to-Income (DTI)

Concept of loan
What Lenders Look For: Eligibility, Income, and Debt-to-Income (DTI)
4:22

Applying for financing can feel overwhelming, but understanding the core eligibility factors lenders use: income, employment, DTI, credit history, and residency makes the process much smoother. Whether you are buying a house or consolidating debt, getting familiar with these elements is crucial. Before diving into official applications, it is helpful to have the prequalification vs preapproval process explained: prequalification gives a rough estimate of your borrowing power, while preapproval involves a verified deep dive into your finances.

Income and Employment Stability

To meet basic personal loan requirements, financial institutions want assurance that you can comfortably repay what you borrow. They look closely at stable vs variable income for lenders; consistent, predictable salaries are typically preferred, though fluctuating freelance earnings are acceptable with proper documentation. You must meet specific income requirements for loan products by providing verifiable proof of income for loan approval, such as W-2s, recent pay stubs, or tax returns.

Furthermore, underwriters check your job stability. For instance, the minimum employment history for mortgage eligibility is usually two consecutive years working in the same industry.

Mastering Your Debt-to-Income Ratio (DTI)

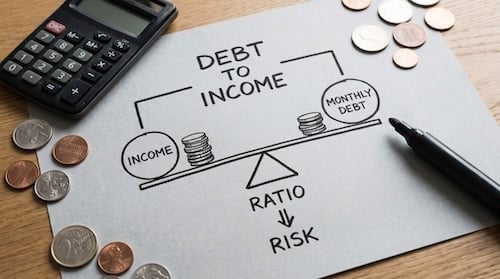
Your debt-to-income ratio is a critical metric for any financial product. If you are wondering how to calculate debt-to-income ratio for loans, simply divide your total monthly debt payments by your gross monthly income. High debt obligations are among the most common reasons for loan application denial.

Here are a few quick DTI facts to keep in mind:

  • The maximum DTI ratio for conventional loans typically caps at 43%, though lower is always better.
  • An ideal DTI for personal loan approval is usually below 36%.
  • The impact of student loans on borrowing power can heavily skew your DTI, limiting how much new credit you can access.
  • Do not confuse terms: understanding debt-to-income ratio vs loan-to-value ratio is essential, as the latter compares a requested loan amount to an asset’s appraised value rather than evaluating your income.

Credit History: The Trust Factor

Your past credit behavior directly dictates your current personal loan eligibility. Strict underwriting guidelines for prime lenders require a solid financial track record to secure the best offers. Institutions often weigh a FICO score vs VantageScore for mortgage lending or personal credit, but universally, a higher score wins.

Understanding how credit score affects loan interest rates is simple: excellent scores unlock significantly lower rates, saving you thousands over time. Because of this, improving credit history before applying for credit—by paying down credit card balances and disputing reporting errors—is a highly recommended strategy.

Residency and Final Approval Checks

Beyond your wallet, your identity and location matter. Providing proof of residency requirements for personal loans (like a recent utility bill, mortgage statement, or lease) is a standard verification step. If you are not a U.S. citizen, do not worry; there are specific loan options for non-permanent resident aliens who possess a valid visa and a current Employment Authorization Document (EAD).

The Bottom Line

Ultimately, mastering these lender approval factors puts you in the driver's seat. By optimizing your income documentation, proactively lowering your debt, and polishing your credit profile, you can confidently secure the best possible terms for your next financial goal.

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Managing rent or a mortgage, utilities, credit cards, insurance, subscriptions, medical bills, and loan payments can make an ordinary month feel...
Continue Reading
Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Debt consolidation is worth it when the new loan's rate, fees, and repayment term genuinely improve your current situation—not just your monthly...

Continue Reading
Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

A consolidation loan is worth considering when the new terms genuinely improve your situation—not just because it replaces several payments with one....

Continue Reading
Can a Consolidation Loan Improve Your Debt-to-Income Ratio?

Can a Consolidation Loan Improve Your Debt-to-Income Ratio?

Explore how a consolidation loan can impact your debt-to-income ratio, and learn what factors to consider before making a decision for your future.

Continue Reading
Debt Options for People on Disability or a Fixed Income

Debt Options for People on Disability or a Fixed Income

Explore effective debt management strategies for individuals on a fixed income, including budgeting tips, repayment options, & debt consolidation...

Continue Reading
Bridging a Temporary Income Gap: How to Borrow Without Getting Stuck

Bridging a Temporary Income Gap: How to Borrow Without Getting Stuck

Discover effective strategies to manage a temporary income gap, including smart borrowing options and budgeting tips to avoid long-term debt.

Continue Reading