Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

2 min read

Why Traditional Budgeting Fails Most People (And It’s Not a Willpower Problem)

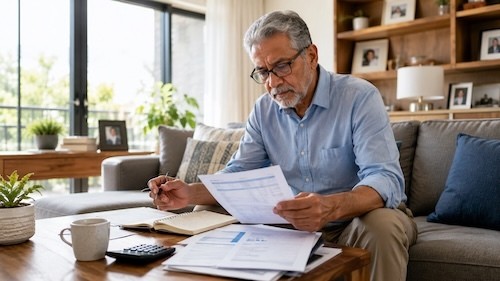
Senior man reviewing bills and financial documents at home, managing expenses, budgeting, retirement planning, and personal finances.
Why Traditional Budgeting Fails Most People
5:02

Traditional budgeting fails because it relies on willpower, rigid rules, and unrealistic assumptions about how people spend, earn, and make decisions. For many US consumers, the issue is not laziness or lack of discipline; it is that traditional budgeting often ignores irregular income, rising living costs, debt obligations, and real-life tradeoffs. This article explains why budgeting fails so often and sets up more practical, modern budgeting alternatives for everyday money management.

Why Does Traditional Budgeting Fail for So Many People?

Traditional budgeting fails because it asks people to predict and control too many variables with too little flexibility. A typical monthly budget assumes income arrives on schedule, expenses stay predictable, and every spending decision can be managed through self-control. That may look clean on paper, but it often breaks down when a utility bill changes, a medical copay appears, groceries cost more than expected, or a car repair disrupts the entire plan.

For US households managing credit cards, student loans, auto loans, rent or mortgage payments, insurance premiums, and everyday essentials, money is rarely static. A rigid budget can turn one unexpected expense into a sense of failure. When that happens repeatedly, people often stop budgeting altogether.

Willpower is the Wrong Foundation

Budgeting without willpower does not mean spending without limits. It means building a system that reduces the number of decisions you have to make under pressure. Traditional budgeting often depends on constant tracking, repeated restraint, and perfect follow-through. That approach becomes difficult when people are tired, stressed, busy, or dealing with competing priorities.

Good personal finance basics should account for human behavior. People are more likely to stick with a plan when bills are organized, savings are automated where possible, and spending categories reflect actual habits rather than idealized goals. A budget should support decision-making, not punish normal life.

Common Budgeting Mistakes That Make Plans Harder to Follow

Many budgeting mistakes come from using a plan that is too strict or too disconnected from real spending patterns. Before blaming yourself, look for structural problems in the budget itself.

  • Ignoring irregular expenses: Annual fees, holiday spending, school costs, insurance renewals, and home or car maintenance can derail a monthly plan.
  • Using unrealistic category limits: If grocery, gas, or childcare estimates are too low, the budget will fail even when spending is reasonable.
  • Treating every month the same: Income, bills, and obligations often vary, especially for hourly, freelance, commission-based, or gig workers.
  • Tracking too much detail: Overly complex spreadsheets or apps can create fatigue instead of clarity.
  • Leaving out debt strategy: Minimum payments may keep accounts current, but they may not create a path toward financial progress.

Modern Budgeting Alternatives Focus on Systems

Modern budgeting alternatives are usually more flexible and behavior-friendly. Instead of forcing every dollar into a rigid category, these methods prioritize cash flow, essential bills, debt payments, savings goals, and planned spending.

A practical approach may include:

  1. List fixed obligations first, including housing, utilities, insurance, loan payments, and minimum debt payments.
  2. Estimate flexible essentials, such as groceries, transportation, and medical costs, using recent spending instead of guesses.
  3. Set aside money for irregular expenses before they become emergencies.
  4. Automate savings or debt payments when possible.
  5. Review the plan weekly or biweekly, especially around paydays.

These money management tips help turn budgeting from a willpower test into a repeatable system.

The Takeaway

If traditional budgeting has not worked for you, the problem may be the method, not your character. A more effective plan should be realistic, flexible, and designed around how money actually moves through your household. The next step is learning which alternatives can help you manage spending, reduce stress, and make steady progress.

Read our full blog post here: https://symplelending.com/insights/why-traditional-budgeting-fails-most-people

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

Why Traditional Budgeting Fails Most People (And It’s Not a Willpower Problem)

Why Traditional Budgeting Fails Most People (And It’s Not a Willpower Problem)

Traditional budgeting fails because it relies on willpower, rigid rules, and unrealistic assumptions about how people spend, earn, and make...
Continue Reading
Does Debt Consolidation Save Money: How to Calculate Whether It Will

Does Debt Consolidation Save Money: How to Calculate Whether It Will

Debt consolidation saves money only when the projected total cost of the new loan is lower than the projected total cost of your current repayment...

Continue Reading
Avoid These Debt Consolidation Pitfalls: Credit Impact, New Spending, and Hidden Fees

Avoid These Debt Consolidation Pitfalls: Credit Impact, New Spending, and Hidden Fees

Debt consolidation can simplify multiple credit card bills, personal loans, or medical balances into one monthly payment. For many US consumers, it...

Continue Reading