Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

3 min read

How to Share Costs When One Partner Has Debt (Without Resentment)

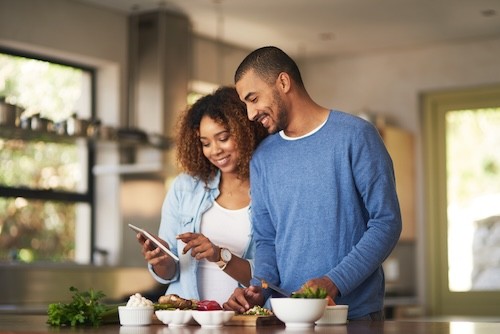
Using a step by step online recipe. Shot of a happy young couple using a digital tablet while preparing a healthy meal together at home.
How to Share Costs When One Partner Has Debt (Without Resentment)
5:22

When one partner brings debt into a relationship, shared expenses can feel more complicated than simply splitting everything 50/50. The goal is not to punish the person with debt or overload the other partner, but to create a fair system that supports everyday bills, a realistic debt repayment plan, and long-term financial trust. For couples and debt, the healthiest approach usually starts with transparency, not blame.

What Is A Fair Way To Split Costs When One Partner Has Debt?

A fair approach considers income, required debt payments, shared goals, and each person’s ability to contribute without falling behind. For many US couples, fair expense sharing with debt means dividing household costs proportionally rather than equally, especially when one partner has student loans, credit card balances, medical bills, or a car loan that affects monthly cash flow.

For example, if one partner earns 60% of the combined household income and the other earns 40%, shared rent, utilities, groceries, and insurance premiums may be split the same way. This can feel more balanced than a strict 50/50 split when one person is carrying mandatory payments. It also keeps the focus on teamwork instead of scorekeeping.

Start With A Full Financial Snapshot

Debt in relationships becomes more stressful when details are vague. Before choosing a cost-sharing method, set aside time to review the basics together: balances, minimum payments, interest rates, due dates, income, credit scores, savings, and recurring expenses. This conversation may be uncomfortable, but it helps both partners make decisions based on facts.

A useful review can include:

  • Monthly take-home pay for each partner
  • Required debt payments, including student loans and marriage-related financial obligations
  • Shared household expenses, such as rent, mortgage, utilities, groceries, and insurance
  • Individual expenses, such as personal subscriptions, hobbies, or separate family support
  • Savings goals, emergency funds, and retirement contributions
  • Credit accounts that could affect protecting credit for one or both partners

Choose A Cost-Sharing Method That Reduces Resentment

The best system is one both partners understand and can maintain. Some couples keep finances separate and contribute to a joint account for shared bills. Others combine most income but set clear limits for personal spending and debt payoff. There is no single correct method, but the agreement should feel predictable and documented.

Common options include:

  1. Proportional Split: Each partner pays a percentage based on income.
  2. Equal Split With Adjustments: Bills are split 50/50, but the non-debt partner may cover more savings or irregular expenses.
  3. Shared Essentials, Separate Debts: Household bills are shared, while each person remains responsible for debts brought into the relationship.
  4. Temporary Support Plan: One partner contributes more for a defined period while the other accelerates repayment.

Whatever you choose, revisit the plan when income, debt balances, or living costs change.

How Can Couples Protect Credit While Paying Down Debt?

Couples can protect credit by paying every account on time, avoiding unnecessary joint debt, and understanding how shared accounts affect both credit profiles. In the US, marriage itself does not merge credit reports, but joint loans, co-signed accounts, and missed payments on shared obligations can affect both partners.

If one partner has debt, be cautious before co-signing, adding authorized users, or opening new joint credit cards. A stronger approach may be to build an emergency fund, automate minimum payments, and use extra funds strategically toward high-interest balances. This supports the debt repayment plan without putting both partners’ credit at risk.

Keep The Conversation Practical And Ongoing

Money conversations work best when they are scheduled, specific, and calm. Instead of discussing debt only during conflict, consider a monthly check-in to review bills, progress, and upcoming expenses. Keep the tone focused on problem-solving: what is working, what feels unfair, and what needs to change?

Learning how to share costs when one partner has debt without resentment is really about building a system that respects both people. With clear numbers, shared expectations, and regular adjustments, couples can manage debt without letting it define the relationship.

Read our full blog post here: https://symplelending.com/insights/11-smart-ways-to-share-expenses-without-stress-in-your-relationship

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

How to Share Costs When One Partner Has Debt (Without Resentment)

How to Share Costs When One Partner Has Debt (Without Resentment)

When one partner brings debt into a relationship, shared expenses can feel more complicated than simply splitting everything 50/50. The goal is not...
Continue Reading
Can You Consolidate Credit Cards and Personal Loans Together?

Can You Consolidate Credit Cards and Personal Loans Together?

Yes, you can sometimes consolidate credit cards and personal loans together using a new personal loan, depending on lender requirements, available...

Continue Reading
Handling Uneven Incomes, Bonuses, and Freelance Pay When Sharing Expenses

Handling Uneven Incomes, Bonuses, and Freelance Pay When Sharing Expenses

When two people share bills, income rarely lines up perfectly. One partner may earn a steady salary while the other receives commissions, bonuses,...

Continue Reading