Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

3 min read

The Reset: How to Assess Your Current Financial Situation After a Setback

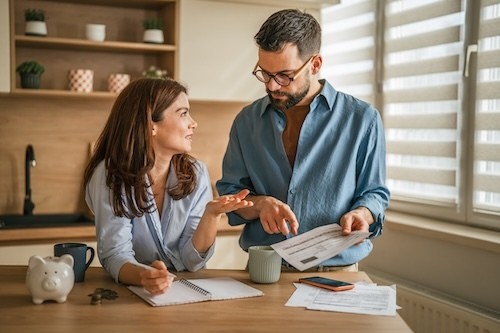
Couple discussing monthly budget and managing household finances
How to Assess Your Current Financial Situation After a Setback
5:14

A financial setback can make your next steps feel unclear, but a structured review can turn uncertainty into a practical plan. This reset focuses on gathering facts, understanding cash flow, and rebuilding financial goals based on your current reality. For US consumers, that also means reviewing credit reports, tax records, loan statements, and household obligations before making major decisions.

Where Should You Start After A Financial Setback?

Start by taking inventory, not by making immediate cuts everywhere. To assess financial situation clearly, you need a complete picture of income, expenses, debts, assets, and upcoming obligations. The goal is to separate what is urgent from what is adjustable, then create a short-term plan that protects essentials while you stabilize.

Useful first steps include:

  • List current income from wages, benefits, self-employment, or temporary support.
  • Identify essential expenses such as housing, utilities, food, insurance, transportation, and minimum debt payments.
  • Note past-due balances, late fees, collection notices, or payment arrangements.
  • Review cash on hand, checking and savings balances, and available emergency funds.
  • Check your credit reports for unfamiliar accounts, errors, or missed-payment reporting.

US consumers can request free weekly credit reports from the three nationwide credit bureaus through AnnualCreditReport.com, the official source identified by the FTC. This is especially useful after job loss, medical bills, divorce, fraud, or another disruption that may affect accounts. (consumer.ftc.gov)

Gather The Financial Documents That Show The Full Picture

A reset is easier when your financial documents are in one place. Collect recent bank and credit card statements, mortgage or lease documents, auto loan records, student loan information, insurance bills, medical bills, pay stubs, and benefit notices. For tax-related income records, include W-2s, 1099s, 1098s, and any IRS transcripts you may need; the IRS notes that wage and income transcripts show information reported on forms such as W-2, 1099, 1098, and 5498. (irs.gov)

Create a simple digital or paper folder by category:

  1. Income: Pay stubs, benefits, freelance income, tax forms.
  2. Spending: Bank statements, card statements, recurring bills.
  3. Debt: Loan balances, interest rates, minimum payments, due dates.
  4. Assets: Savings, retirement accounts, vehicles, home equity estimates.
  5. Risk Items: Insurance policies, legal notices, medical balances, collection letters.

This file becomes your financial checkup hub.

Use A Net Worth Worksheet To Reset Your Baseline

A net worth worksheet is a simple snapshot: assets minus liabilities. It does not judge progress; it gives you a starting number. Include cash, savings, retirement accounts, taxable investments, vehicles, and property on one side, then credit cards, loans, medical debt, and other balances on the other.

After a setback, your net worth may be lower than expected. That is still useful information because it helps you decide whether to focus first on cash flow, debt stabilization, savings, or rebuilding assets.

Build A Practical Budget Around Today’s Cash Flow

Budgeting after setback should be realistic, not idealized. Track expenses for at least a few weeks so your plan reflects actual behavior rather than estimates. The CFPB suggests using a personal finance tool or even a notebook to record expenses, which can help reveal patterns that are easy to miss. (consumerfinance.gov)

Then divide spending into three groups: essential, adjustable, and temporary pauses. Essentials protect housing, food, transportation, insurance, and required payments. Adjustable costs may include subscriptions, dining, entertainment, or nonurgent purchases.

Turn The Review Into Financial Goals

Once the facts are visible, set financial goals in stages. A near-term goal may be catching up on one overdue bill or building a small cash buffer. A mid-term goal may be reducing high-interest debt or restoring automatic savings. A longer-term goal may involve retirement contributions, homeownership planning, or rebuilding credit strength.

The reset is not a one-time exercise. Repeat your financial checkup monthly until conditions stabilize, then quarterly as your plan becomes more predictable.

Read our full blog post here: https://symplelending.com/insights/turning-setbacks-into-strategy-for-financial-resilience

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

The Reset: How to Assess Your Current Financial Situation After a Setback

The Reset: How to Assess Your Current Financial Situation After a Setback

A financial setback can make your next steps feel unclear, but a structured review can turn uncertainty into a practical plan. This reset focuses on...
Continue Reading
Refinance vs Debt Consolidation: Which Strategy Fits Your Goals?

Refinance vs Debt Consolidation: Which Strategy Fits Your Goals?

Refinancing replaces one existing loan with new terms, while debt consolidation combines several balances into one repayment obligation. The...

Continue Reading
Why Financial Setbacks Feel So Discouraging (And Why They Don’t Define Your Future)

Why Financial Setbacks Feel So Discouraging (And Why They Don’t Define Your Future)

Financial setbacks can affect more than a bank balance. A job loss, medical bill, missed payment, or rising credit card balance can create financial...

Continue Reading