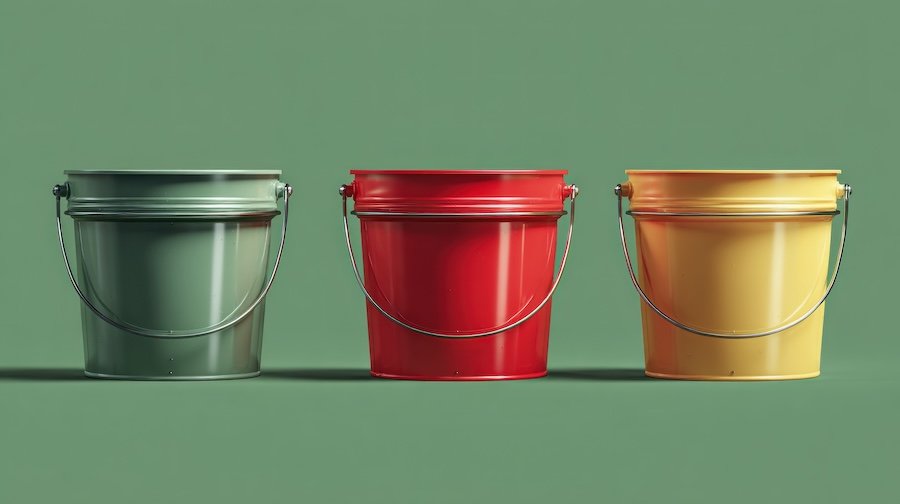
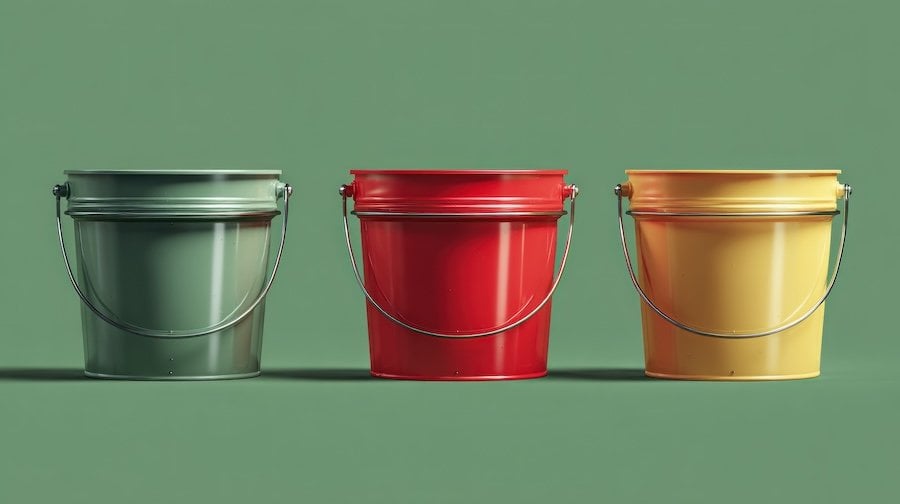
A Simpler Alternative: The 3-Bucket Budget for Real Life
A 3 bucket budget is a simple budgeting method that groups your money into three broad areas: essentials, goals, and lifestyle. Instead of tracking...
Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.
Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.
Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.
Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.
Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.
A 3 bucket budget is a simple budgeting method that groups your money into three broad areas: essentials, goals, and lifestyle. Instead of tracking dozens of detailed budget categories, this approach gives US consumers a practical spending plan that is easier to maintain month after month. It works especially well for budgeting for beginners who want structure without turning money management into a second job.
The 3-bucket method is a personal finance system that organizes after-tax income into three clear buckets: what you must pay, what you want to build, and what you choose to enjoy. Essentials cover required living costs, goals support savings and debt priorities, and lifestyle includes flexible spending. By simplifying decisions, the method helps you see whether your money is aligned with real life rather than a spreadsheet.
This does not mean you ignore details. You still review bills, balances, and due dates. The difference is that you manage categories at a useful level, so your plan remains realistic when grocery prices change, an insurance premium renews, or an unexpected expense appears.
Essentials are the costs required to keep your household running. For many US consumers, this may include rent or mortgage payments, utilities, groceries, minimum debt payments, insurance, transportation, childcare, and basic medical costs.
Goals are the financial priorities that move you forward. This bucket can include emergency savings, retirement contributions, extra debt payments, a home down payment, education savings, or a planned major purchase.
Lifestyle includes the spending that makes life more flexible and enjoyable. Dining out, subscriptions, hobbies, travel, gifts, entertainment, and personal shopping usually fit here. This bucket is not “bad” spending; it simply needs a boundary.
Start with your monthly take-home pay, then assign every dollar to one of the three buckets before the month begins. A simple example allocation could be 60% essentials, 20% goals, and 20% lifestyle. If your after-tax income is $5,000 per month, that would mean $3,000 for essentials, $1,000 for goals, and $1,000 for lifestyle.
Use this as a starting point, not a rule. A household in a high-cost city may need more for essentials, while someone paying down credit card debt may temporarily increase the goals bucket. The right allocation is the one that covers obligations, protects progress, and leaves room for sustainable choices.
Use this template to build your first version:
A detailed line-item budget can be useful, but it often fails when it becomes too time-consuming. The 3-bucket approach reduces friction by focusing on the decisions that matter most: covering needs, funding progress, and controlling flexible spending. For many people, that balance makes the system easier to repeat.
Read our full blog post here: https://symplelending.com/insights/why-traditional-budgeting-fails-most-people
Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.
A 3 bucket budget is a simple budgeting method that groups your money into three broad areas: essentials, goals, and lifestyle. Instead of tracking...
Consolidation before and after means comparing your debt costs before replacing multiple credit card balances with one personal loan and after, using...
A household budget can look balanced on paper and still feel difficult in real life. For many US consumers, the issue is not only how much income...