Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

2 min read

Monthly Budgeting 101: The Simple Framework That Actually Works

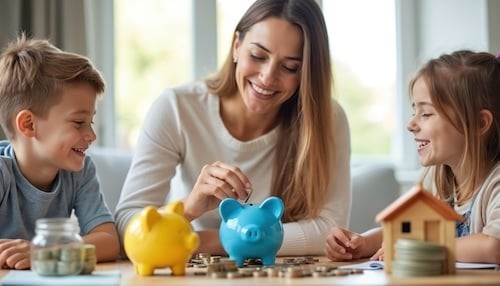
Mother teaches kids saving money with piggy banks and coins on table. Children learn about finance and budgeting with parent at home. Family counts cash and plans future.
Monthly Budgeting 101: The Simple Framework That Actually Works
4:24

A monthly budget is a practical plan for how your money comes in, goes out, and supports your goals. For anyone learning budgeting for beginners, the process works best when it is simple, repeatable, and easy to adjust. This guide covers monthly budgeting basics for US consumers: a simple framework that works without requiring complicated tools.

What Is A Monthly Budget?

A monthly budget is a written plan that matches your expected income with your expected expenses for one month. It helps you decide what must be paid first, what can be reduced, and how much can go toward savings, debt, or other priorities. The purpose is not to restrict every choice; it is to give every dollar a clear job before the month begins.

A Simple Budget Framework That Works

A strong budget framework starts with clarity. Instead of guessing where your money goes, review your income, bills, everyday spending, and financial goals. Once those pieces are visible, you can make decisions based on facts rather than stress.

Use this basic structure:

  1. List Monthly Income: Include take-home pay and any reliable recurring income.
  2. Identify Fixed Expenses: Add rent or mortgage, utilities, insurance, loan payments, subscriptions, and other regular bills.
  3. Estimate Variable Spending: Include groceries, gas, dining, personal care, entertainment, and household needs.
  4. Set Savings And Debt Goals: Decide what you can put toward emergency savings, retirement, extra debt payments, or upcoming expenses.
  5. Compare Income And Spending: If expenses are higher than income, adjust flexible categories first.
  6. Track And Review: Check your progress weekly so small issues do not become month-end surprises.

This approach keeps budgeting basics manageable. It also gives you a clear monthly routine instead of a one-time exercise.

How To Budget When Income Or Expenses Change

To budget when income or expenses change, update your plan as soon as you know the new numbers. A monthly budget should be flexible enough to handle seasonal bills, reduced hours, extra income, medical costs, school expenses, or car repairs. The key is to protect essentials first, then adjust lower-priority spending.

If your income varies, build your budget around a conservative estimate. When extra money comes in, direct it toward savings, debt reduction, or upcoming bills before adding more discretionary spending. This keeps your plan steady even when the month is not predictable.

Practical Personal Finance Tips For Staying Consistent

The best budget is the one you can actually maintain. Start with a format that fits your habits, such as a spreadsheet, budgeting app, notebook, or banking worksheet. Accuracy matters more than the tool.

Helpful personal finance tips include:

  • Review your accounts at the same time each week.
  • Separate needs, wants, and goals before cutting expenses.
  • Plan for irregular costs, such as gifts, maintenance, or annual fees.
  • Keep one small category for flexible spending so the budget feels realistic.
  • Use reminders for due dates to avoid missed payments.
  • Revisit your plan after major life changes.

Learning how to budget takes practice. The first month may not be perfect, but each review improves your understanding of your spending patterns.

The Takeaway

A monthly budget works when it is clear, realistic, and reviewed regularly. Start with income, organize expenses, choose goals, and make adjustments before problems build. With a simple framework, budgeting becomes less about restriction and more about making informed choices.

Read our full blog post here: https://symplelending.com/insights/how-to-create-a-monthly-budget-that-works-step-by-step-guide

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Managing rent or a mortgage, utilities, credit cards, insurance, subscriptions, medical bills, and loan payments can make an ordinary month feel...
Continue Reading
Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Debt consolidation is worth it when the new loan's rate, fees, and repayment term genuinely improve your current situation—not just your monthly...

Continue Reading
Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

A consolidation loan is worth considering when the new terms genuinely improve your situation—not just because it replaces several payments with one....

Continue Reading
A Step-by-Step Checklist to Pick the Right Loan Terms for Your Goal

A Step-by-Step Checklist to Pick the Right Loan Terms for Your Goal

Learn how to choose the right loan terms for your financial goals with our step-by-step checklist, ensuring affordability and practicality.

Continue Reading
Read Before You Sign: The Consolidation Loan Fine Print

Read Before You Sign: The Consolidation Loan Fine Print

Before signing a consolidation loan, understand the fine print, including rates, fees, and repayment terms to make a well-informed financial decision.

Continue Reading
What Does a Consolidation Loan Actually Cost? Consolidation Loan Fees and Terms

What Does a Consolidation Loan Actually Cost? Consolidation Loan Fees and Terms

Explore the true costs of consolidation loans, including fees, interest rates, and repayment terms, to make informed financial decisions.

Continue Reading