Skip to the main content.

Personal Loans

Whether you're covering unexpected expenses, making a big purchase, or just need extra cash, our personal loans offer simple, flexible funding tailored to your needs.

Learn more...

Consolidation Loans

Simplify your finances with a loan that combines multiple payments into one. Our consolidation loans help reduce stress and keep your budget on track.

Learn more...

Home Improvement Loans

Upgrade your living space with financing designed for renovations, repairs, or remodeling. Our home improvement loans help you enhance your home’s comfort, value, and functionality—on your terms.

Learn more...

Symple Insights

Explore expert insights, financial tips, and strategic guidance from the Symple Lending team. Our insights and resource articles are your go-to source for empowering content that helps you make informed decisions on your journey to financial freedom.

Learn More...

Symple News

Stay up-to-date with the latest press releases, media features, and major announcements from Symple Lending. This section showcases how we're making headlines and driving innovation in the lending industry.

Learn More...

2 min read

Build Sinking Funds For Irregular Expenses (So They Stop Wrecking Your Budget)

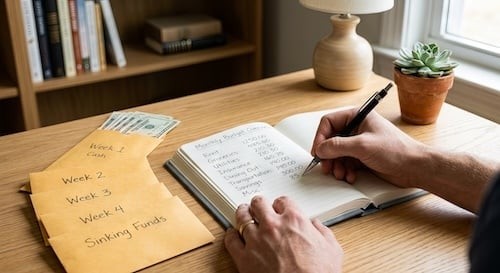
Personal finance budgeting system showing monthly budget overview notebook handwritten expenses cash envelopes labeled weeks savings funds wooden desk lifestyle concept stock photography for buyers
Build Sinking Funds For Irregular Expenses
4:17

Irregular expenses can make a balanced monthly budget feel unreliable. Sinking funds help you prepare for known costs before they arrive, so bills like insurance, gifts, subscriptions, and car repairs do not force you into debt or emergency savings. For US consumers, this step turns surprise spending into planned spending.

How Do You Build Sinking Funds For Irregular Expenses So They Do Not Break Your Budget?

You build sinking funds by listing predictable but non-monthly costs, estimating each annual total, dividing that number by 12, and saving that amount every month. This simple method works because it spreads large or uneven expenses across the year. Instead of finding hundreds of dollars at once, you create smaller monthly targets that fit into your regular budget.

Start with the categories most likely to disrupt your cash flow. Common sinking funds include:

  • Car Repairs Budget: Oil changes, tires, registration, maintenance, and unexpected repairs.
  • Holiday Budget: Gifts, travel, meals, decorations, and seasonal events.
  • Insurance: Annual or semiannual premiums for auto, renters, homeowners, or other coverage.
  • Subscriptions: Annual software, streaming, memberships, apps, or professional tools.
  • Gifts: Birthdays, weddings, graduations, baby showers, and other planned occasions.

The goal is not to predict every dollar perfectly. The goal is to reduce the number of expenses that catch you unprepared.

Sinking Funds Make Annual Expenses Easier To Manage

An annual expenses budget helps you see the full cost of a year, not just the bills due this month. Review bank and credit card statements from the past 12 months and mark expenses that happen once, twice, or a few times per year. If you paid $1,200 for insurance premiums last year, saving $100 per month gives that bill a clear place in your budget.

Use separate savings buckets if your bank allows them, or track each fund in a spreadsheet or budgeting app. Name each category clearly, such as “Car Repairs,” “Holiday Budget,” or “Annual Subscriptions.” Clear labels make it easier to avoid using the money for daily spending.

Emergency Fund Vs Sinking Fund

An emergency fund is for unexpected financial shocks, while a sinking fund is for expected expenses that do not happen every month. A sudden job loss, medical bill, or urgent home repair may belong in your emergency fund. A car registration renewal, holiday gifts, or annual insurance premium belongs in a sinking fund because you can plan for it in advance.

Keeping these funds separate protects both goals. If you use emergency savings for predictable costs, you may not have enough left when a real emergency happens. If you use sinking funds correctly, your emergency fund can stay focused on true uncertainty.

A Simple Monthly Process To Follow

Use this process once per month when you review your budget:

  1. List upcoming irregular expenses for the next 3 to 12 months.
  2. Estimate the cost of each item based on past spending or current bills.
  3. Divide the total by the number of months remaining before payment is due.
  4. Add those amounts to your monthly budget as savings line items.
  5. Review balances monthly and adjust when costs change.

This approach makes sinking funds practical, not complicated. Over time, you will rely less on credit cards, reduce budget stress, and gain a clearer picture of your real cost of living.

Read our full blog post here: https://symplelending.com/insights/how-to-create-a-monthly-budget-that-works-step-by-step-guide

Disclaimer: The information provided in this blog post is for educational and informational purposes only and should not be considered as financial, legal, investment, or tax advice. Symple Lending is not responsible for any financial outcomes resulting from following the information or ideas shared in this blog. Every individual's financial situation is unique, and we strongly encourage readers to take their own circumstances into consideration and consult with a qualified financial, legal, tax, and investment advisor before making any financial decisions. Symple Lending does not provide financial, legal, tax, or investment advice.

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Why Multiple Monthly Bills Feel Unmanageable (and What to Do First)

Managing rent or a mortgage, utilities, credit cards, insurance, subscriptions, medical bills, and loan payments can make an ordinary month feel...
Continue Reading
Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Is Debt Consolidation Worth It? 7 Questions to Answer Before You Apply

Debt consolidation is worth it when the new loan's rate, fees, and repayment term genuinely improve your current situation—not just your monthly...

Continue Reading
Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

Is a Consolidation Loan a Good Idea? Run the Before-and-After Math

A consolidation loan is worth considering when the new terms genuinely improve your situation—not just because it replaces several payments with one....

Continue Reading
Can You Buy a House With Credit Card Debt?

Can You Buy a House With Credit Card Debt?

Discover how credit card debt impacts homebuying. Learn strategies for balancing debt and savings to achieve your homeownership goals.

Continue Reading
How Paying Off Debt Affects Your Mortgage Application

How Paying Off Debt Affects Your Mortgage Application

Discover how paying off debt impacts your mortgage application, from credit scores to DTI ratios, and learn the best strategies for financial...

Continue Reading
Track Spending Fast—The 15-Minute Method For Busy People

Track Spending Fast—The 15-Minute Method For Busy People

Discover a quick 15-minute method to track your spending and stay on budget without overwhelming yourself. Simplify your financial routine today.

Continue Reading